Everything homeowners need for home equity loans, in one place.

Ontario homeowners come to us for home equity loans, lines of credit, second mortgages, refinancing, renewals and reverse mortgages, to lower their payments, clear high-rate balances or stop a power of sale. We’re a licensed brokerage working with lenders who care more about your equity than your income or credit score.

Tell us what’s going on. We’ll show you your options and take care of the rest.

★★★★★Google Reviews
Trusted by 2,400+ Ontario homeowners

Who you’ll talk to

Matthew
Will
Marko
★★★★★

“Will provided excellent information and helped me through each step of the process.”

Laura, Google review

Same-day call back. No judgement. No pressure.

See what I qualify for
24hrsConditional approvals
70+Lenders compared
25+ yrsCombined experience
Lenders we work with
TD BankHome TrustMCAN FinancialFirst National FinancialCMLS FinancialEquitable Bank
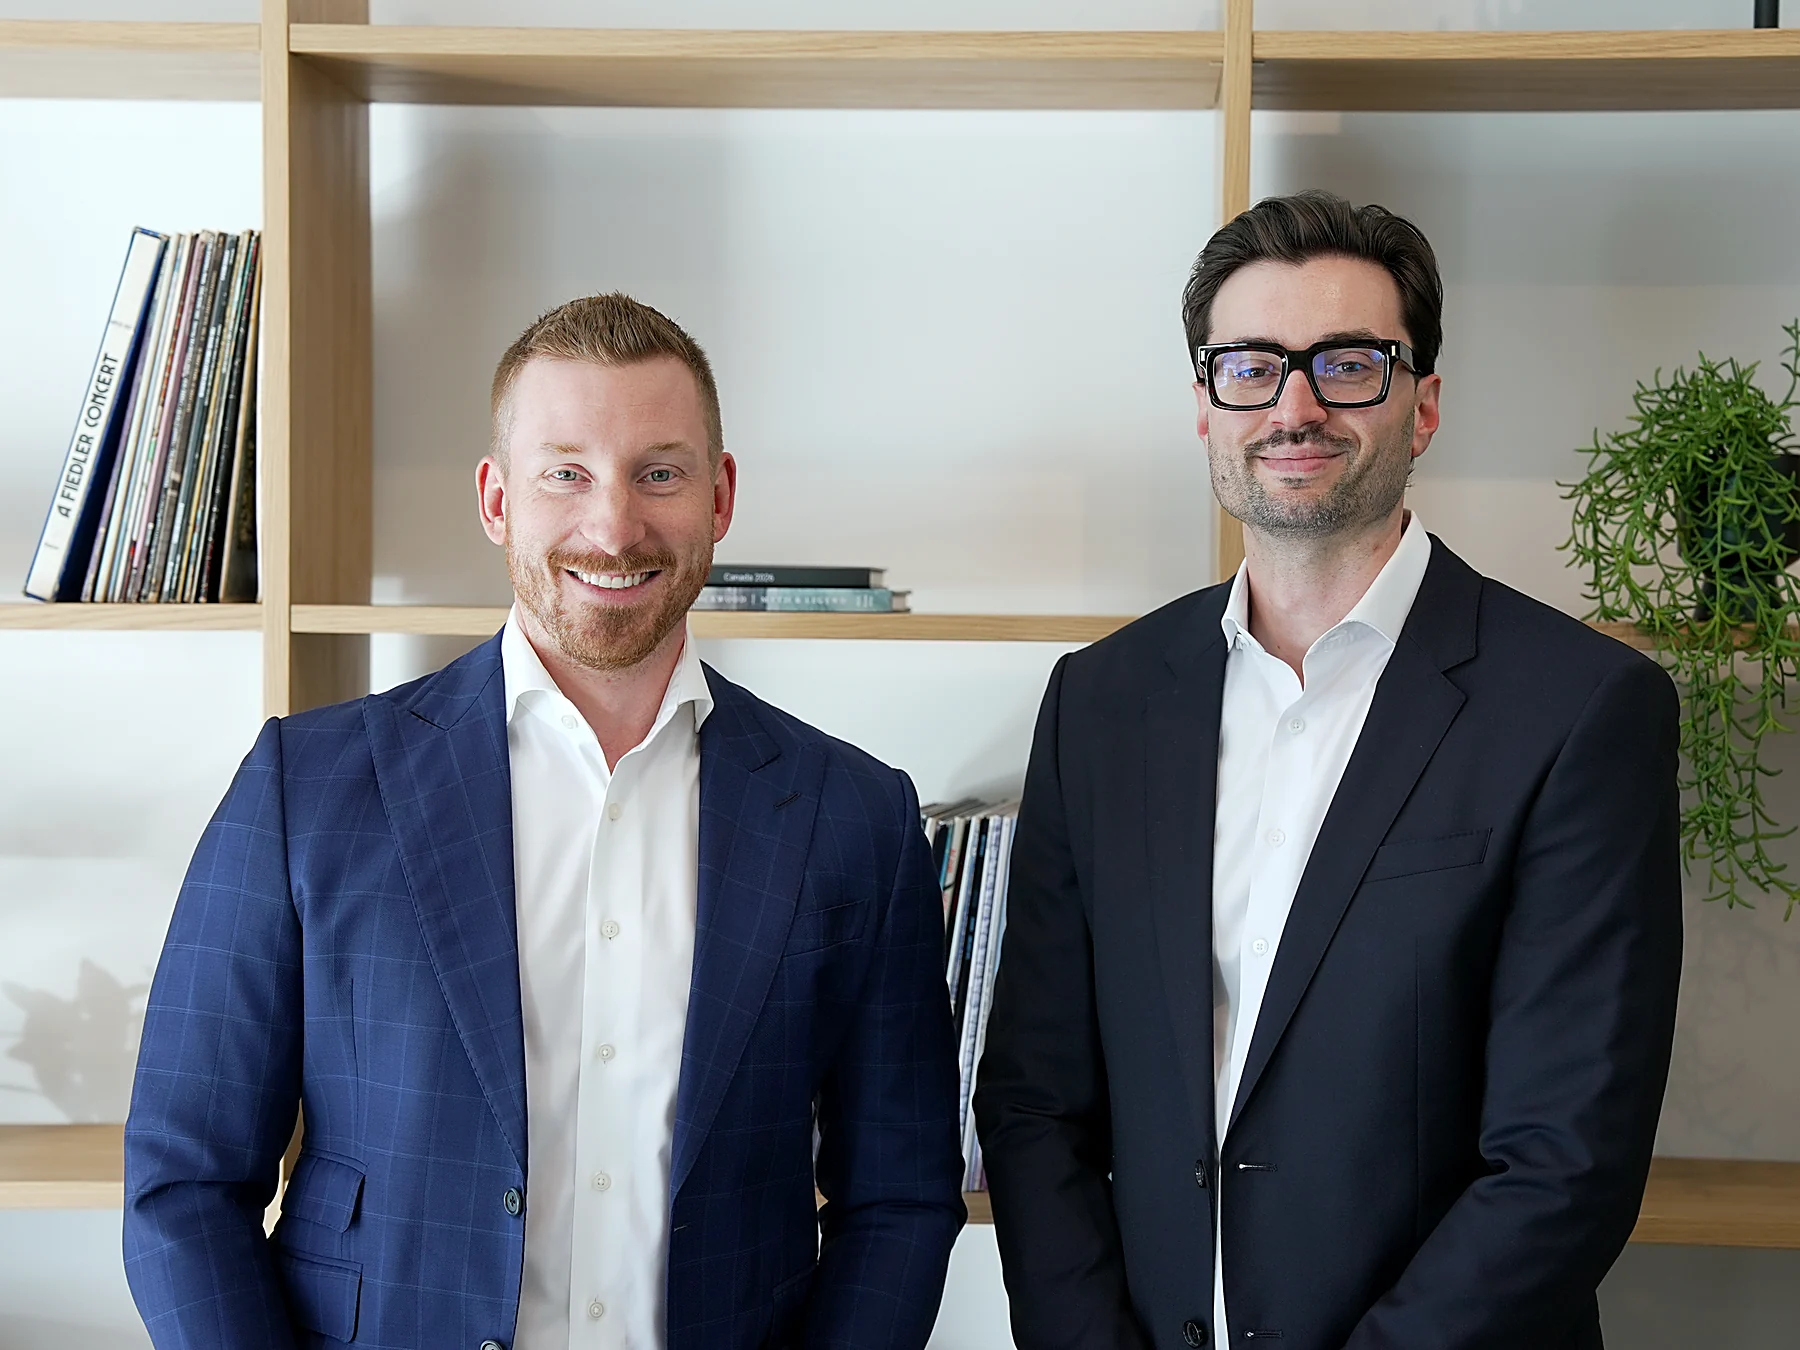
Matt and Marko at the Lighthouse Lending office

You’re in good hands

We started Lighthouse so Ontario homeowners would have someone in their corner who listens first. More than 2,400 homeowners later, that’s still how every conversation starts.

Whatever brought you here, you’ll talk with someone who has seen it before and won’t judge. We’ll tell you what’s possible, lay out your options and stay with you until your mortgage closes.

Matt and MarkoLighthouse Lending

Two homeowners. Two big wins.

$114,102
in balances, consolidated

The credit cards, gone.

The bank said no early on, because their payments were too high for its limits. Each month their credit score slipped and fewer options were left. We matched them with a different lender and got them a new mortgage in 27 days.

$3,605less to pay every month
$129,783saved over a 3-year term
$56,000
in property tax arrears, paid off

They kept their home.

They were one month from auction and had been told no so many times they worried no one could help. It took about 4 calls and a week to fund, with a plan to get them back to a bank, and we did it.

Home keptno auction
First mortgagein place of the private loan

What would one lower payment free you up to do?

See what I qualify for

From Lighthouse clients, with names left out for privacy. Your numbers will depend on your home, your lender and your situation.

Whatever brought you here, we can help

Tell us how we can help and we’ll match you with the right product.

Who we can help, and when we can’t

We can help
If you own a home in Ontario and have equity in it

Employed, self-employed or not working right now. Rebuilding credit or behind on payments. We start with the equity in your home, then work through your situation with you.

We can’t help
If you rent, or you’re buying your first home

We need a home with equity in it to work with, so we’re not the right fit for first-time home buyers. If your home doesn’t have enough equity yet, we’ll tell you on the first call.

One team for every option

Whatever your situation, one team takes care of it from the first call to closing. Want to read up first? Pick a service. Or tell us what’s going on and we’ll match you.

What it looks like to use your home equity with us

Clear answers up front, so you know what to expect before you call.

70+
Ontario lenders we compare for you

One conversation replaces going bank to bank. We compare your options for you.

Clear
Every option explained simply

We lay out what each option means for your month, side by side, and tell you which one we’d pick and why, so you can decide.

Your pace
You decide when to move

Ask every question you have, for as long as you need. We ask before any credit check, and nothing moves ahead until you say so.

How it works

Three steps, and you only have to do the first one.

1

Tell us what’s going on

A few quick questions online, or a call if you’d rather talk it through.

No pressure
2

We find the right fit

We look across banks, credit unions and private lenders, then walk you through your options and why they fit.

Options side by side
3

We take care of the rest

Once you say yes, we handle the lender, the loan application and the paperwork through to closing.

Nothing to chase

Home equity loans, refinancing and your other options: what each one does

Each option can allow you to access equity in a different way. Here’s what each one does, in plain words.

How a home equity loan works

A home equity loan lets you borrow against the equity in your home. Your equity is the market value of your home minus what you still owe on your existing mortgage. You take out a loan for a set loan amount and get it as one lump sum, then repay it on a set schedule. It’s a secured loan: a home equity loan uses your home as collateral, so it often comes with a lower interest rate than a credit card.

How a home equity line of credit (HELOC) works

A home equity line of credit, often referred to as a HELOC, is a credit line secured by your home. A HELOC allows you to borrow what you need, when you need it, up to your line of credit amount, and you pay interest on the amount you use. It’s revolving credit, so whatever you pay back goes back into your available credit line. Use your line of credit as costs come up.

Second mortgage or refinance: which fits?

A second mortgage leaves your first in place and adds a second monthly payment. A refinance replaces your mortgage with a larger one, so you keep one payment. We check which one fits before you decide.

When does refinancing make sense?

More often than people think. A refinance replaces your mortgage loan with a larger one, so you can borrow a larger amount and keep one mortgage payment. A lower mortgage rate, stronger credit or high-interest balances you’d like to roll into one payment are all good reasons. Timing matters: breaking a mortgage early comes with a penalty, so we check first that the savings are worth it. Refinancing at renewal has no penalty. If the penalty doesn’t add up, we’ll look at a second mortgage, which gets you the cash without touching your existing mortgage.

Mortgage renewal

Your lender sends a renewal offer a few months before your term ends. You don’t have to take it: switching lenders at renewal usually has no penalty. We compare the market for you, so you sign the best offer, not the first one.

Reverse mortgage in Ontario

Homeowners 55 and over can turn the equity in their home into tax-free cash, with no required monthly payments, and stay in the home they love. How much you can access depends on your age, your home value and your location.

Consolidate high-rate balances

Roll credit cards and other high-rate balances into one mortgage payment and breathe easier each month. We check that the savings are worth it before you decide.

Stop a power of sale in Ontario

In Ontario, most lenders use a power of sale rather than a foreclosure, so the two often mean the same thing to a homeowner. Either way, the equity in your home can often pay what you owe and stop the process. Tell us the date on your notice and we’ll go through your options.

What is a private mortgage?

A private mortgage comes from a private lender instead of a bank or credit union. Private lenders look at your home equity first, so they can work with rebuilding credit or income that doesn’t fit a bank’s box. The tradeoff: in most cases the rate is higher than a bank’s, so we treat it as a bridge and plan your way back to a bank rate from the start. We work with private mortgage lenders in Ontario and match you with the right one.

How HELOC rates work: fixed or variable interest rate?

A home equity loan usually has a fixed rate. With a fixed interest rate, what you pay each month stays the same. Most HELOCs have a variable interest rate tied to the prime rate, the base rate lenders set their rates from, so what you pay can change when rates move. We’ll walk you through the rates and terms you qualify for, side by side. See how rates compare in our guide to home equity line of credit rates in Ontario.

How much can you borrow from your home equity?

Before you tap into your home equity, it helps to know how much is there. It depends on what your home is worth, what you owe and what the lender looks for in a borrower. Banks usually stop at 80% of your home’s value, counting every mortgage on it. Private lenders can go further, case by case. Tell us what you owe and what your home is worth, and we’ll show you where you stand.

How a home appraisal sets the value of your home

Most lenders ask for a home appraisal and work from the appraised value of your home. An appraiser looks at your home and similar homes nearby to confirm what it’s worth. When the value of your home increases, your home equity increases with it, and you have more available equity to use. We’ll tell you up front if your lender needs an appraisal.

What’s needed for a home equity loan application

Less than you might expect. Usually some detail on your income, whatever it looks like right now, a look at your credit and the value of the property. Pay stubs, tax returns and bank statements follow where needed. If you’re self-employed, bank statements or your personal tax returns can often do it. Missing something? Start anyway. We’ll help you get it.

How homeowners use their equity

Homeowners use their equity to clear high-rate balances and lower what they pay each month. Some use the equity to pay off property tax arrears, or to pay for home renovations, home repairs and other home improvements. It’s a way to access your equity without having to sell your home.

Borrowing against your home: is a home equity loan the right choice?

You don’t need to know the product names. Working that out is our job. Here’s what we’d pick in three common situations.

Borrowing in stages.

We’d look at a HELOC, so you pay interest on what you use.

The tradeoff: your rate can move, so your payment can too.

One known amount.

We’d look at a home equity loan, with one set payment.

The tradeoff: you pay interest on the full amount from day one.

The bank said no.

We’d look at a second mortgage, which leaves your first in place.

The tradeoff: it usually comes at a higher rate than your first.
Why homeowners choose Lighthouse

How you’re treated matters as much as the rate.

You’re heard first

We start with what you’re trying to do, not with a product to sell, and we won’t judge.

Every situation welcome

Self-employed, retired, rebuilding credit or behind on payments: we’ve helped people in your spot.

Licensed and regulated

Regulated by FSRA (#13301), Ontario’s financial services regulator. Everyone you’ll talk to here is licensed.

Help at renewal, and after

We keep an eye on your renewal, so the first offer in the mail isn’t your only choice when the time comes.

A couple sitting on the front steps of their Ontario home on a fall afternoon

What homeowners say

From our Google reviews, in their own words.

★★★★★

“I had an amazing experience working with Marko as my mortgage broker! He was incredibly helpful, professional, and responsive throughout the entire process. He worked quickly to help me secure my mortgage and made what could have been a stressful and overwhelming experience feel smooth and straightforward.”

Sara K.
Google review
★★★★★

“Matthew was wonderful to work with. He remained calm and collected every moment of our transaction (Even when I became emotional) and handled everything with the professionalism and integrity. Highly recommend Matthew and the team at Lighthouse Lending!”

Jenna B.
Google review
★★★★★

“I had a great experience working with William at Lighthouse Lending during my remortgage. Will was very easy to deal with, always responded promptly to my calls and texts, and took the time to explain any concerns I had along the way.”

Justin S.
Google review
★★★★★

“Matthew is very patient and professional. Him and his team truly care for the people they work for - I have referred friends who never felt pressure to commit and Matthew is generous with his time and knowledge.”

Emma H.
Google review
★★★★★

“I highly recommend working with Lighthouse Lending. I had a great experience with William. He really explained the process and my options. The whole process was very simple and efficient.”

Rozalie J.
Google review
★★★★★

“I had worked with Marko, he was very good at navigating us through the process and was able to get us the loan we needed, being self employed borrowing money can be tricky Marko was great at helping out with what was needed for the process.”

Troy P.
Google review

Questions homeowners ask before they decide

Quick answers. For the details on any one product, our guides go deeper.

Can I get a home equity loan if the bank said no?

Often, yes. One bank’s answer isn’t the final one. Private lenders look at your home equity first, so rebuilding credit or income that doesn’t fit a bank’s box doesn’t have to end the conversation. You don’t need a good credit score to ask. If there’s a way, we’ll find it, and we’ll tell you if there isn’t.

Can I pay off a second or private mortgage?

Often, yes. If your credit has improved or you have more equity now, you may be able to replace a second mortgage or private mortgage with one new mortgage and one payment. We’ll check that the savings are worth it, including any penalty, before you decide.

How fast can I get approved?

Many clients have a conditional approval within 24 hours. Full funding typically follows within a few days to a few weeks, depending on the product and your situation. If you’re working against a deadline, tell us up front and we’ll plan around it.

Will talking to you affect my credit score?

Talking to us doesn’t affect it. We can go through your situation and give you an initial sense of your options first. We’ll always ask before any step that involves a credit check.

I’m behind on my mortgage. What can I do?

Call us as soon as you can. Things in life happen, and missed mortgage payments or mortgage arrears don’t mean you lose your home. If you have equity in your home, we can look at ways to catch up, and we won’t judge.

How do I stop a power of sale in Ontario?

The sooner you call, the more options you have. The equity in your home can often pay what you owe and stop the sale. We’ll go through your options with you.

Can I use my equity to buy out my spouse?

Often, yes. If you’re separating and want to stay in the home, you may be able to refinance or take out a home equity loan to pay your spouse their share of the equity. Your lawyer looks after the separation agreement, and we look after the mortgage.

Where do you work?

Across Ontario, by phone and online. Our office is in Barrie. We help homeowners with home equity loans, HELOCs, reverse mortgages and private mortgages in Toronto, Barrie and the GTA, as well as Mississauga, Hamilton, Ottawa and beyond.

Let’s find the right option for you

Whatever’s going on, we’ve seen it before. Let’s talk it through.